Richemont Balances Luxury Growth With Caution
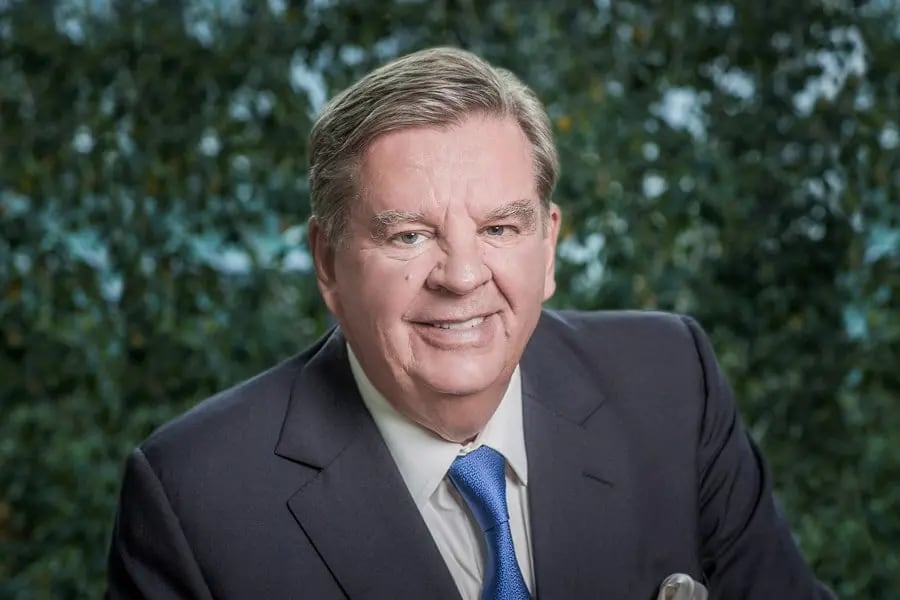
Strong financial results can create pressure on corporate leaders to pursue expansion more aggressively, but Richemont's latest performance has been accompanied by a notably cautious assessment of the international luxury market. The Swiss group behind Cartier and Van Cleef & Arpels reported double-digit sales growth and improved profitability for the six months ending in September, supported by jewellery demand and stronger watch sales. Chairman Johann Rupert nevertheless emphasised the continuing uncertainty created by economic and geopolitical conditions. His comments reflect a central challenge for executives managing established luxury houses: maintaining growth and investor confidence without compromising the qualities that give their brands enduring commercial value.
Richemont reported first-half revenue of approximately €12.3 billion, representing growth of 17% at constant exchange rates, while operating profit increased to €3.1 billion. Its jewellery businesses remained the principal source of strength, with sales growth across most major regions. However, the group continues to face higher raw-material costs and uneven demand between markets. Management has maintained an emphasis on pricing discipline, recognising that repeated increases may eventually affect customer perceptions and demand. The company has also continued investing in manufacturing capabilities, retail networks and the development of its individual maisons. These decisions indicate that leadership is balancing near-term profitability against the need to preserve long-term brand strength.
The results have also brought attention to Richemont's governance and succession arrangements. In September, the company appointed Anton Rupert as non-executive co-deputy chairman alongside Bram Schot. Their responsibilities are intended to be complementary, with Anton focusing on strategic product and communications matters and Schot concentrating on board and committee governance. The appointments form part of the group's longer-term succession planning, an important consideration for a business whose identity has been closely associated with the Rupert family. The arrangements do not amount to an immediate transfer of the chairmanship, but they provide greater clarity about how responsibilities are being distributed within the board.
Richemont's leadership decisions illustrate the distinctive governance challenges facing major luxury groups. Their value depends not only on financial performance but also on creative direction, craftsmanship, brand heritage and relationships with customers. These qualities can be difficult to protect if management becomes excessively focused on short-term sales targets. At the same time, investors expect disciplined capital allocation and evidence that established brands can adapt to changing markets. Richemont's current approach seeks to preserve continuity while strengthening its capacity for future development. The company's results demonstrate the commercial benefits of that strategy, although slower-than-expected jewellery growth also shows that strong performance does not eliminate investor concerns. The longer-term test will be whether leadership can sustain growth without weakening the identity of the businesses responsible for it.